Auro Panorama EMI Calculator
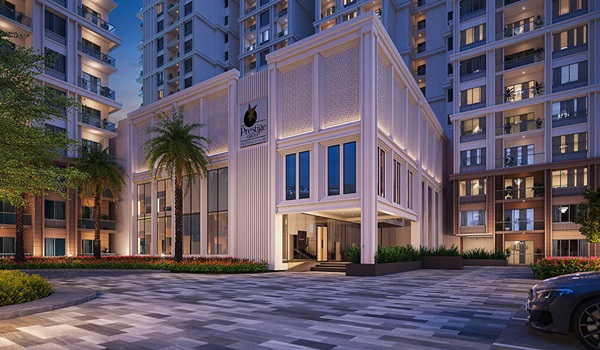
Featured Image of Auro Panorama EMI Calculator


Auro Panorama EMI calculator computes your exact monthly mortgage obligation starting from ₹1,52,860 for an entry-level ₹2.20 Crore 2 BHK unit financed at an 8.50% interest rate over a 20-year repayment tenure. This automated financial estimation tool incorporates property sizes ranging from 1,400 to 2,200 sq. ft. across 2 BHK, 3 BHK, and 4 BHK configurations to project precise principal and interest outflows.

It calculates net borrowing balances by deducting the mandatory 20% equity down payment from the base agreement value, isolating your true loan exposure before you commit capital. Factoring in current banking benchmark rates alongside loan horizons of 15 to 30 years, this calculator ensures prospective homebuyers in Kondapur maintain full visibility over monthly debt serviceability and total compounding interest liabilities.
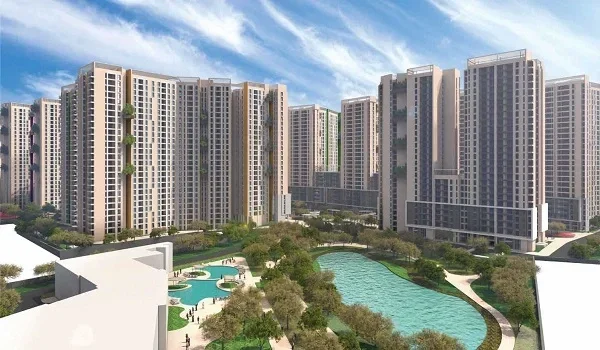
What Is the Auro Panorama EMI Calculator?


The Auro Panorama EMI calculator is an online tool that shows your exact monthly bank payment for homes starting at ₹2.20 Crore in Kondapur. You only need to type in three simple numbers: your loan amount, the bank's yearly interest rate, and the number of years you want to take to pay it back.

The Formula Used: EMI = [P × R × (1 + R)^N] / [(1 + R)^N - 1]

  • Loan Amount (P): The total money the bank gives you after you pay your own 20% down payment.
  • Monthly Interest (R): The yearly interest rate divided by 12 months.
  • Total Months (N): The total time you choose, counted in months (for example, 240 months for 20 years).

In the first few years, most of your monthly payment goes toward bank interest. As time passes, this slowly flips, and more of your money goes to clear the actual property price.

Configuration-Wise EMI Breakup for Auro Panorama


Auro Panorama home prices start at ₹2.20 Crore for a 2 BHK and go up to ₹3.45 Crore for a 4 BHK, meaning your monthly EMI will sit between ₹1,52,860 and ₹2,39,715 under regular bank rates. Here is a clear table that shows your estimated monthly cost when taking an 80% home loan at an 8.50% interest rate for 20 years.

Unit Configuration Super Built-up Area (Sq. Ft.) Estimated Base Price 80% Loan Amount Estimated Monthly EMI (20 Yrs @ 8.50%)
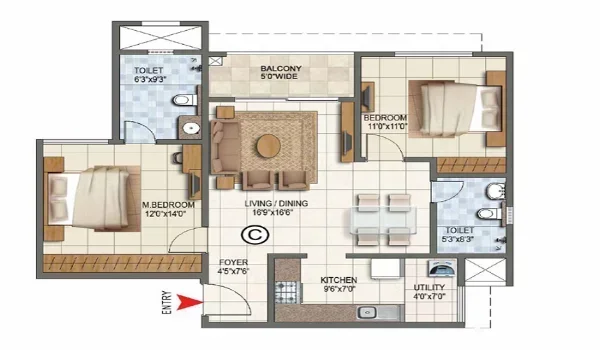
2 BHK Luxury 1,400 – 1,500 ₹2.20 Cr – ₹2.35 Cr ₹1.76 Cr – ₹1.88 Cr ₹1,52,860 – ₹1,63,280
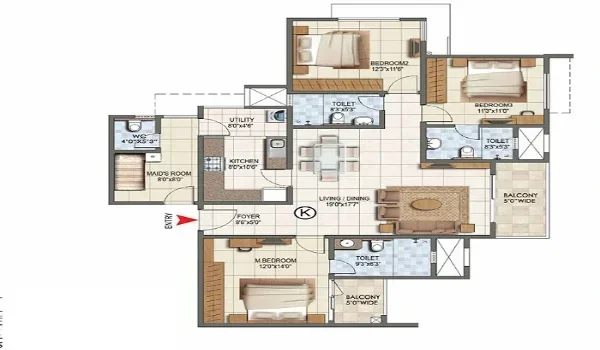
3 BHK Premium 1,700 – 1,860 ₹2.65 Cr – ₹2.90 Cr ₹2.12 Cr – ₹2.32 Cr ₹1,84,130 – ₹2,01,500
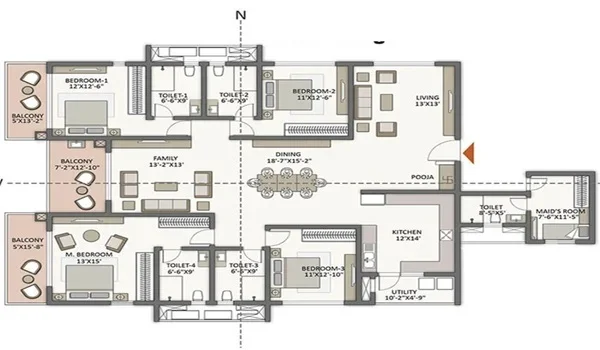
4 BHK Sky Suite 2,000 – 2,200 ₹3.15 Cr – ₹3.45 Cr ₹2.52 Cr – ₹2.76 Cr ₹2,18,870 – ₹2,39,715

Step-by-Step Guide to Calculating Your Monthly EMI


Calculating your monthly installment takes only four clear steps once you have the official price sheet from the builder and a loan sanction letter from your bank. Taking a few minutes to check your numbers keeps your monthly budget safe.

  • Subtract Your 20% Down Payment: Take away at least 20% from the flat price (which starts at ₹44 Lakh for a 2 BHK) to see the final loan amount you need.
  • Pick Your Loan Years: Pick between 15, 20, or 30 years to see what fits your monthly salary best.
  • Add the Bank Interest Rate: Put in the exact rate your bank gave you based on your job profile and credit health.
  • Read the Payment Chart: Check how much the balance drops each year so you can plan part-payments whenever you get extra savings.

Impact of Loan Tenure on Total Interest and EMI


Picking a shorter 15-year loan raises your monthly payment but saves you over 40% on total bank interest compared to a 30-year loan. For example, on a ₹1.76 Crore loan for a 2 BHK flat at 8.50%, a 15-year plan asks for ₹1,73,320 each month, while a 30-year plan asks for just ₹1,35,330 but doubles the extra interest you pay to the bank.

  • 15-Year Plan: Bigger monthly payments, but you clear your full debt fast and pay the lowest total interest.
  • 20-Year Plan: The most popular choice because it balances an easy monthly payment with reasonable interest costs.
  • 30-Year Plan: The smallest monthly payment, but you end up paying more in interest than the actual cost of your flat.

Factors Influencing Your Loan Approval and Interest Rates


Getting your home loan approved quickly requires a healthy CIBIL score above 750 and total monthly debt payments below half of your take-home pay. Banks check your monthly salary slip and credit history before giving you their best interest rate.

  • Your Credit Score: A CIBIL score of 750 or higher gets you the lowest interest rates around 8.40% to 8.60%, while scores below 700 push your rate up.
  • Your Current Debt: Banks make sure that all your current EMIs plus this new home loan do not cross 40% to 50% of your monthly salary.
  • Loan Type: Floating rates change when the Reserve Bank of India moves rates and have zero prepayment charges, while fixed rates stay identical for a set time.

Down Payment and Upfront Capital Requirements


Booking a home at Auro Panorama requires keeping at least 20% cash ready for the down payment, along with extra funds for government taxes that banks do not pay for. For a 2 BHK home priced at ₹2.20 Crore, you will need around ₹60 Lakh to ₹65 Lakh in your bank account to cover all initial costs comfortably.

  • 20% Down Payment: Starts at ₹44 Lakh for 2 BHK, ₹53 Lakh for 3 BHK, and ₹63 Lakh for 4 BHK flats.
  • Telangana Govt Stamp Duty & Registration: Comes to about 7.5% of the flat value, paid directly to the government during registration.
  • GST Charges: A flat 5% GST applies to under-construction flats in Hyderabad.
  • Bank Processing Charges: Banks usually charge a small one-time file fee between ₹15,000 and ₹50,000 to verify papers and approve your loan.

Prepayment Strategies to Reduce Your Interest Burden


Paying small extra amounts directly toward your main loan balance cuts down your total interest and helps you become debt-free years ahead of time. Under RBI rules, banks cannot fine you or charge extra fees for paying off floating-rate home loans early.

  • Pay One Extra EMI Each Year: Paying just one bonus EMI every 12 months can cut a 20-year loan down by almost 4 years.
  • Use Yearly Work Bonuses: Putting a 5% lump sum toward your principal loan amount every year can cut your total interest bill in half.
  • Shorten the Years, Not the EMI: Whenever you pay extra cash, ask the bank to reduce your loan tenure instead of reducing your monthly EMI for the biggest interest savings.

FAQs


1. How is the home loan EMI calculated for a 2 BHK in Auro Panorama?

Home loan EMIs use the standard reducing balance formula: EMI = [P × R × (1 + R)^N] / [(1 + R)^N - 1]. For a ₹2.20 Crore 2 BHK flat with an 80% loan of ₹1.76 Crore at an 8.50% rate over 20 years, your monthly payment comes to ₹1,52,860.

2. What is the minimum down payment needed for Auro Panorama?

Banks usually lend up to 80% of the flat cost, so you need to pay the remaining 20% from your own pocket. For this project, the down payment starts at ₹44 Lakh for a 1,400 sq. ft. 2 BHK unit.

3. Are government stamp duty and registration fees included in the EMI?

No, banks only give loan money for the base cost of the flat and do not include the 7.5% Telangana stamp duty or registration fees in your loan. You have to pay these government taxes yourself during property registration.

4. Can I prepay my Auro Panorama loan early without any fine?

Yes, RBI rules state that banks cannot charge any penalty or extra fee if you make prepayments on a floating-rate home loan. Any extra payment you make goes straight toward cutting your main loan balance.

5. What is the EMI difference between a 15-year and 20-year tenure for a 3 BHK?

For a 3 BHK loan of ₹2.12 Crore at 8.50%, a 15-year term has an EMI of ₹2,08,790 with ₹1.63 Crore in total interest, while a 20-year term drops your EMI to ₹1,84,130 but raises total interest to ₹2.29 Crore.

Enquiry
Enquire Now